An advanced crypto trading bot written in Python
See the code
Algo-trading was 😵💫, we made it 🤩



Jesse is an advanced crypto trading framework that aims to simplify researching and defining YOUR OWN trading strategies for backtesting, optimizing, and live trading.
Watch this video to get a quick overview of Jesse:
In short, Jesse is more accurate than other solutions, and way more simple. In fact, it is so simple that in case you already know Python, you can get started today, in matter of minutes, instead of weeks and months.
Craft complex trading strategies with remarkably simple Python. Access 300+ indicators, multi-symbol/timeframe support, spot/futures trading, partial fills, and risk management tools. Focus on logic, not boilerplate.
class GoldenCross(Strategy):
    def should_long(self):
        # go long when the EMA 8 is above the EMA 21
        short_ema = ta.ema(self.candles, 8)
        long_ema = ta.ema(self.candles, 21)
        return short_ema > long_ema

    def go_long(self):
        entry_price = self.price - 10        # limit buy order at $10 below the current price
        qty = utils.size_to_qty(self.balance*0.05, entry_price) # spend only 5% of my total capital
        self.buy = qty, entry_price                 # submit entry order
        self.take_profit = qty, entry_price*1.2  # take profit at 20% above the entry price
        self.stop_loss = qty, entry_price*0.9   # stop loss at 10% below the entry price
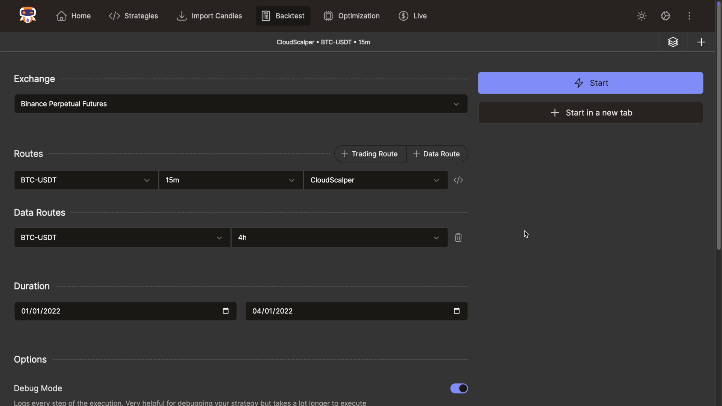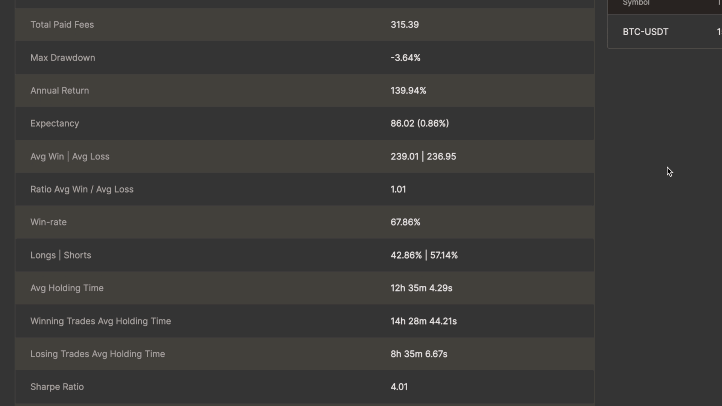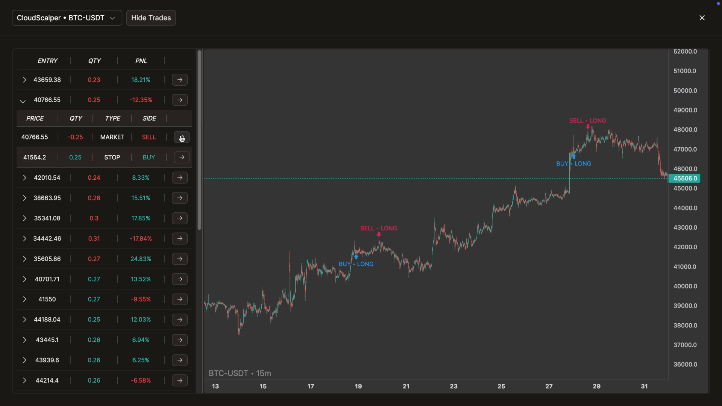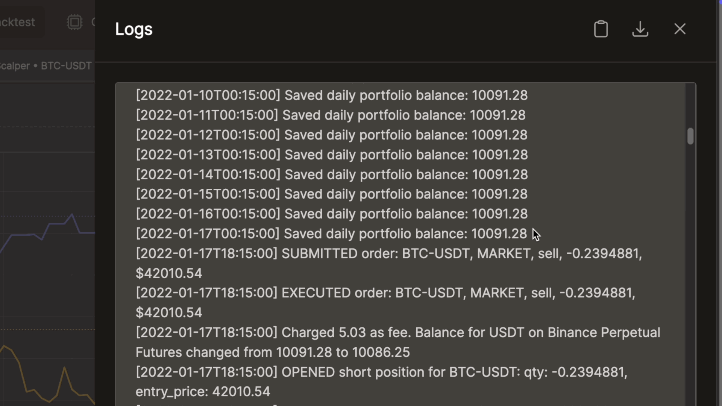
Execute highly accurate and fast backtests without look-ahead bias. Utilize debugging logs, interactive charts with indicator support, and detailed performance metrics to validate your strategies thoroughly.
Inspect your strategy where its decisions happened. Jesse combines candlesticks, strategy-added indicators and levels, executed orders, and completed trades in synchronized interactive charts. The same charting workflow is available for backtests and for running or completed paper/live sessions.
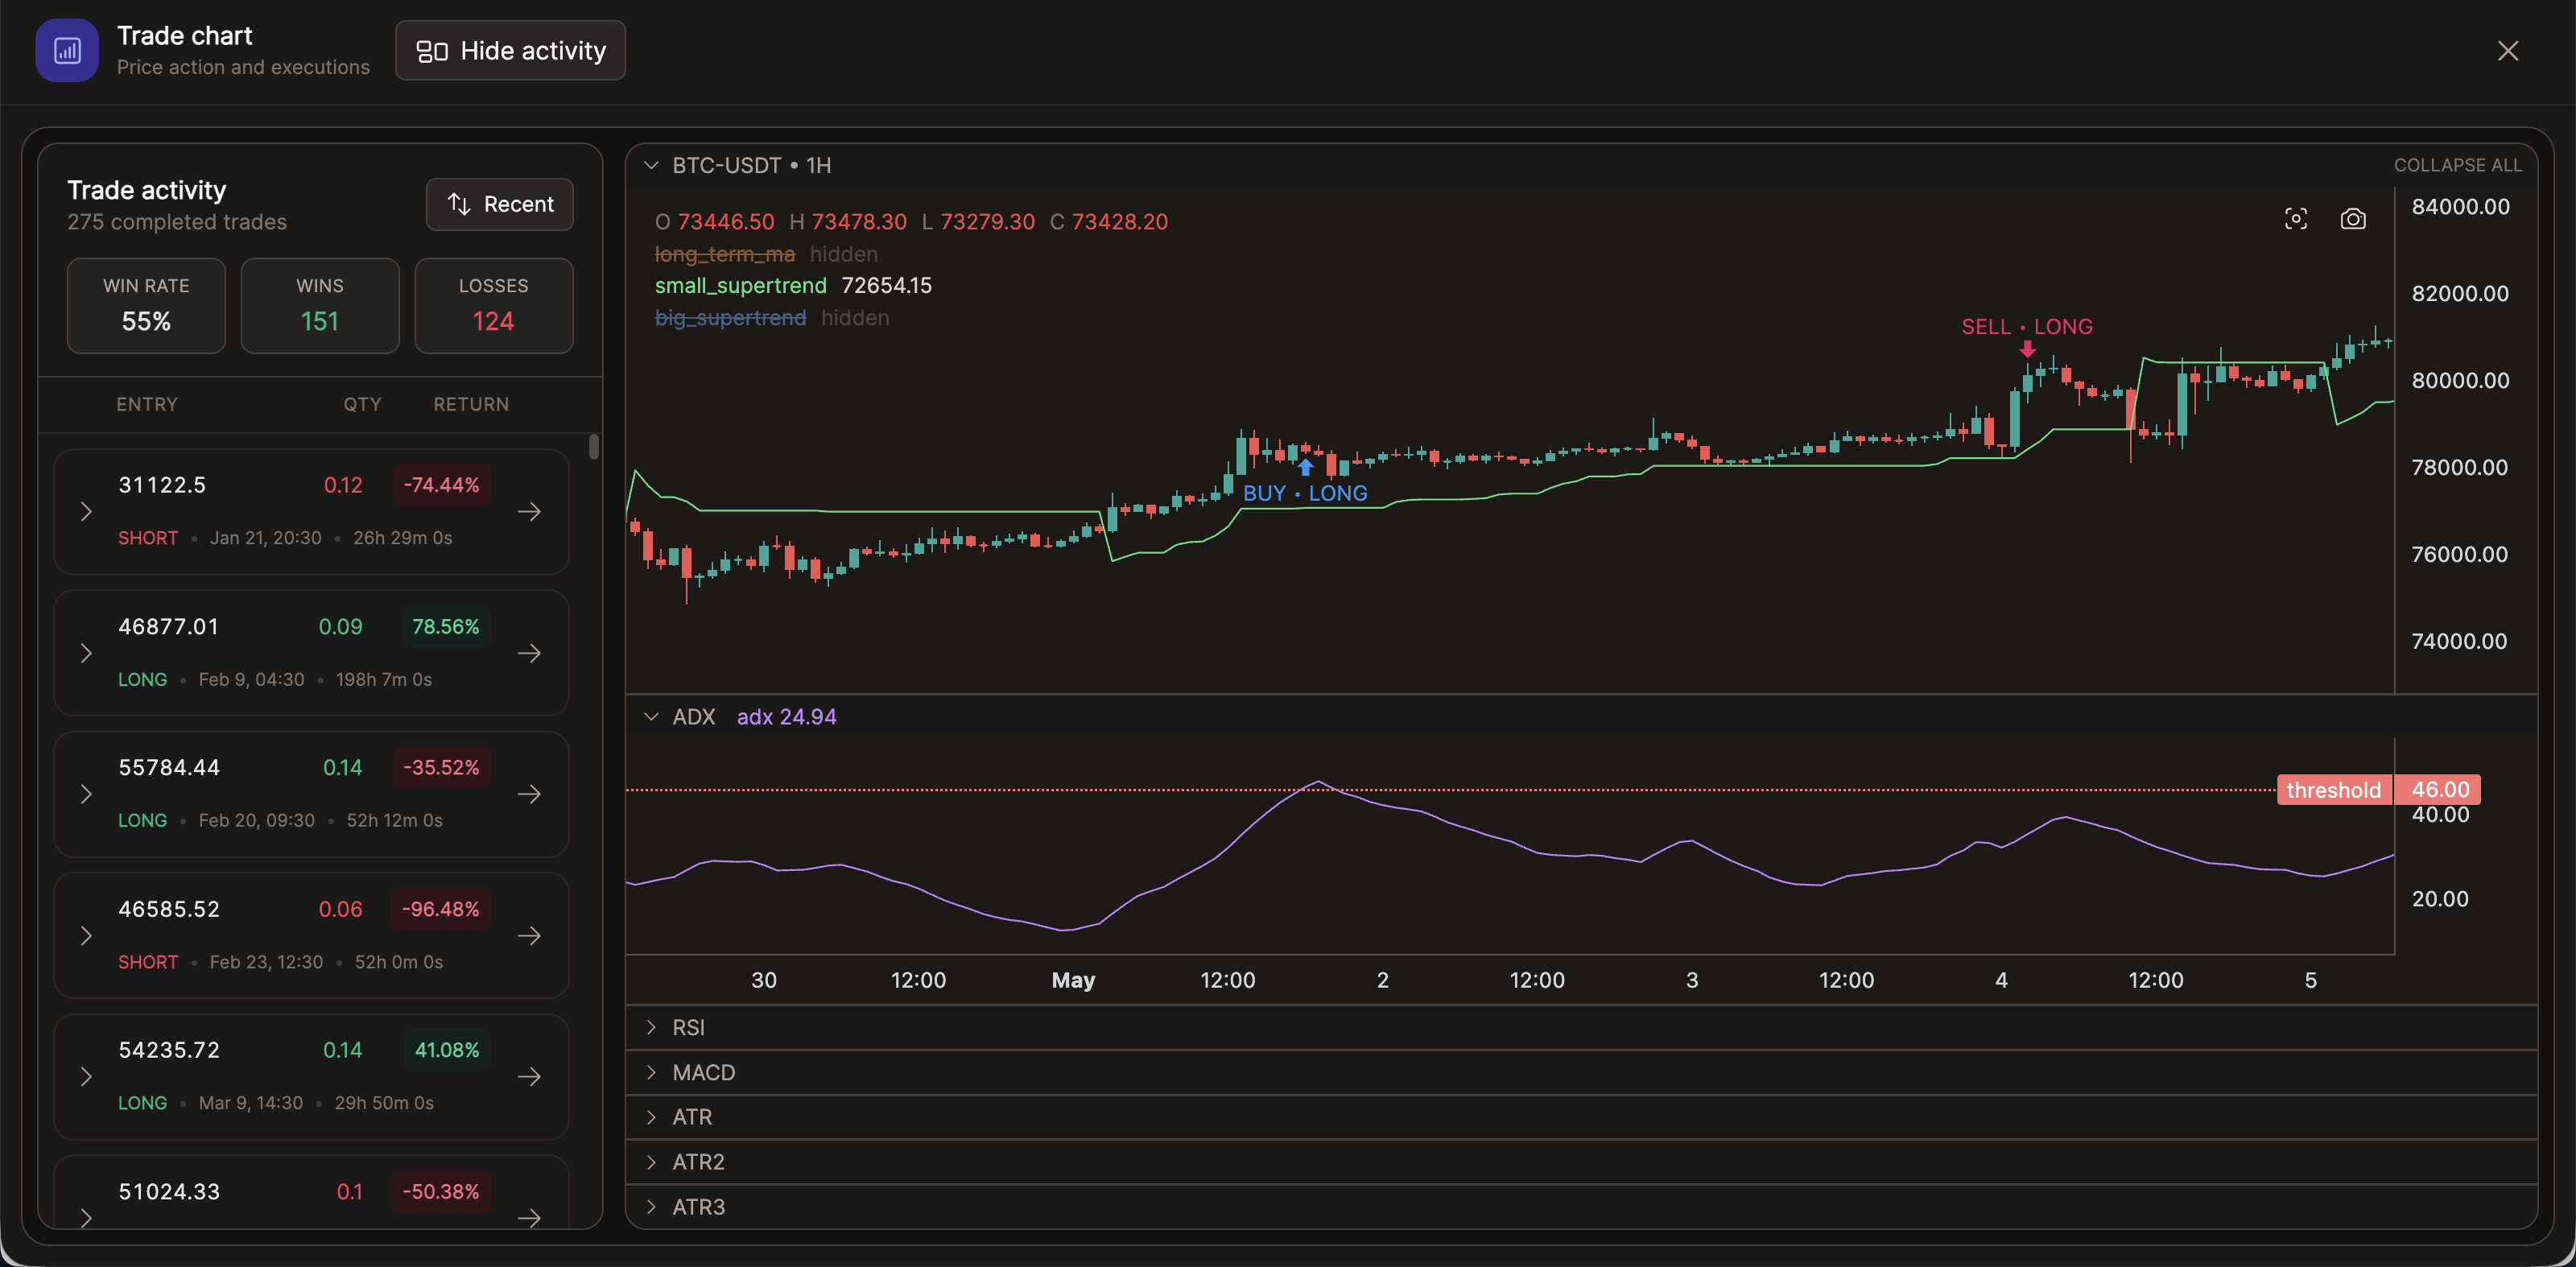
Expand a trade to inspect every execution, collapse or isolate indicator panes, follow OHLC and indicator values under the cursor, reset the view, use fullscreen mode, or export the chart as an image.
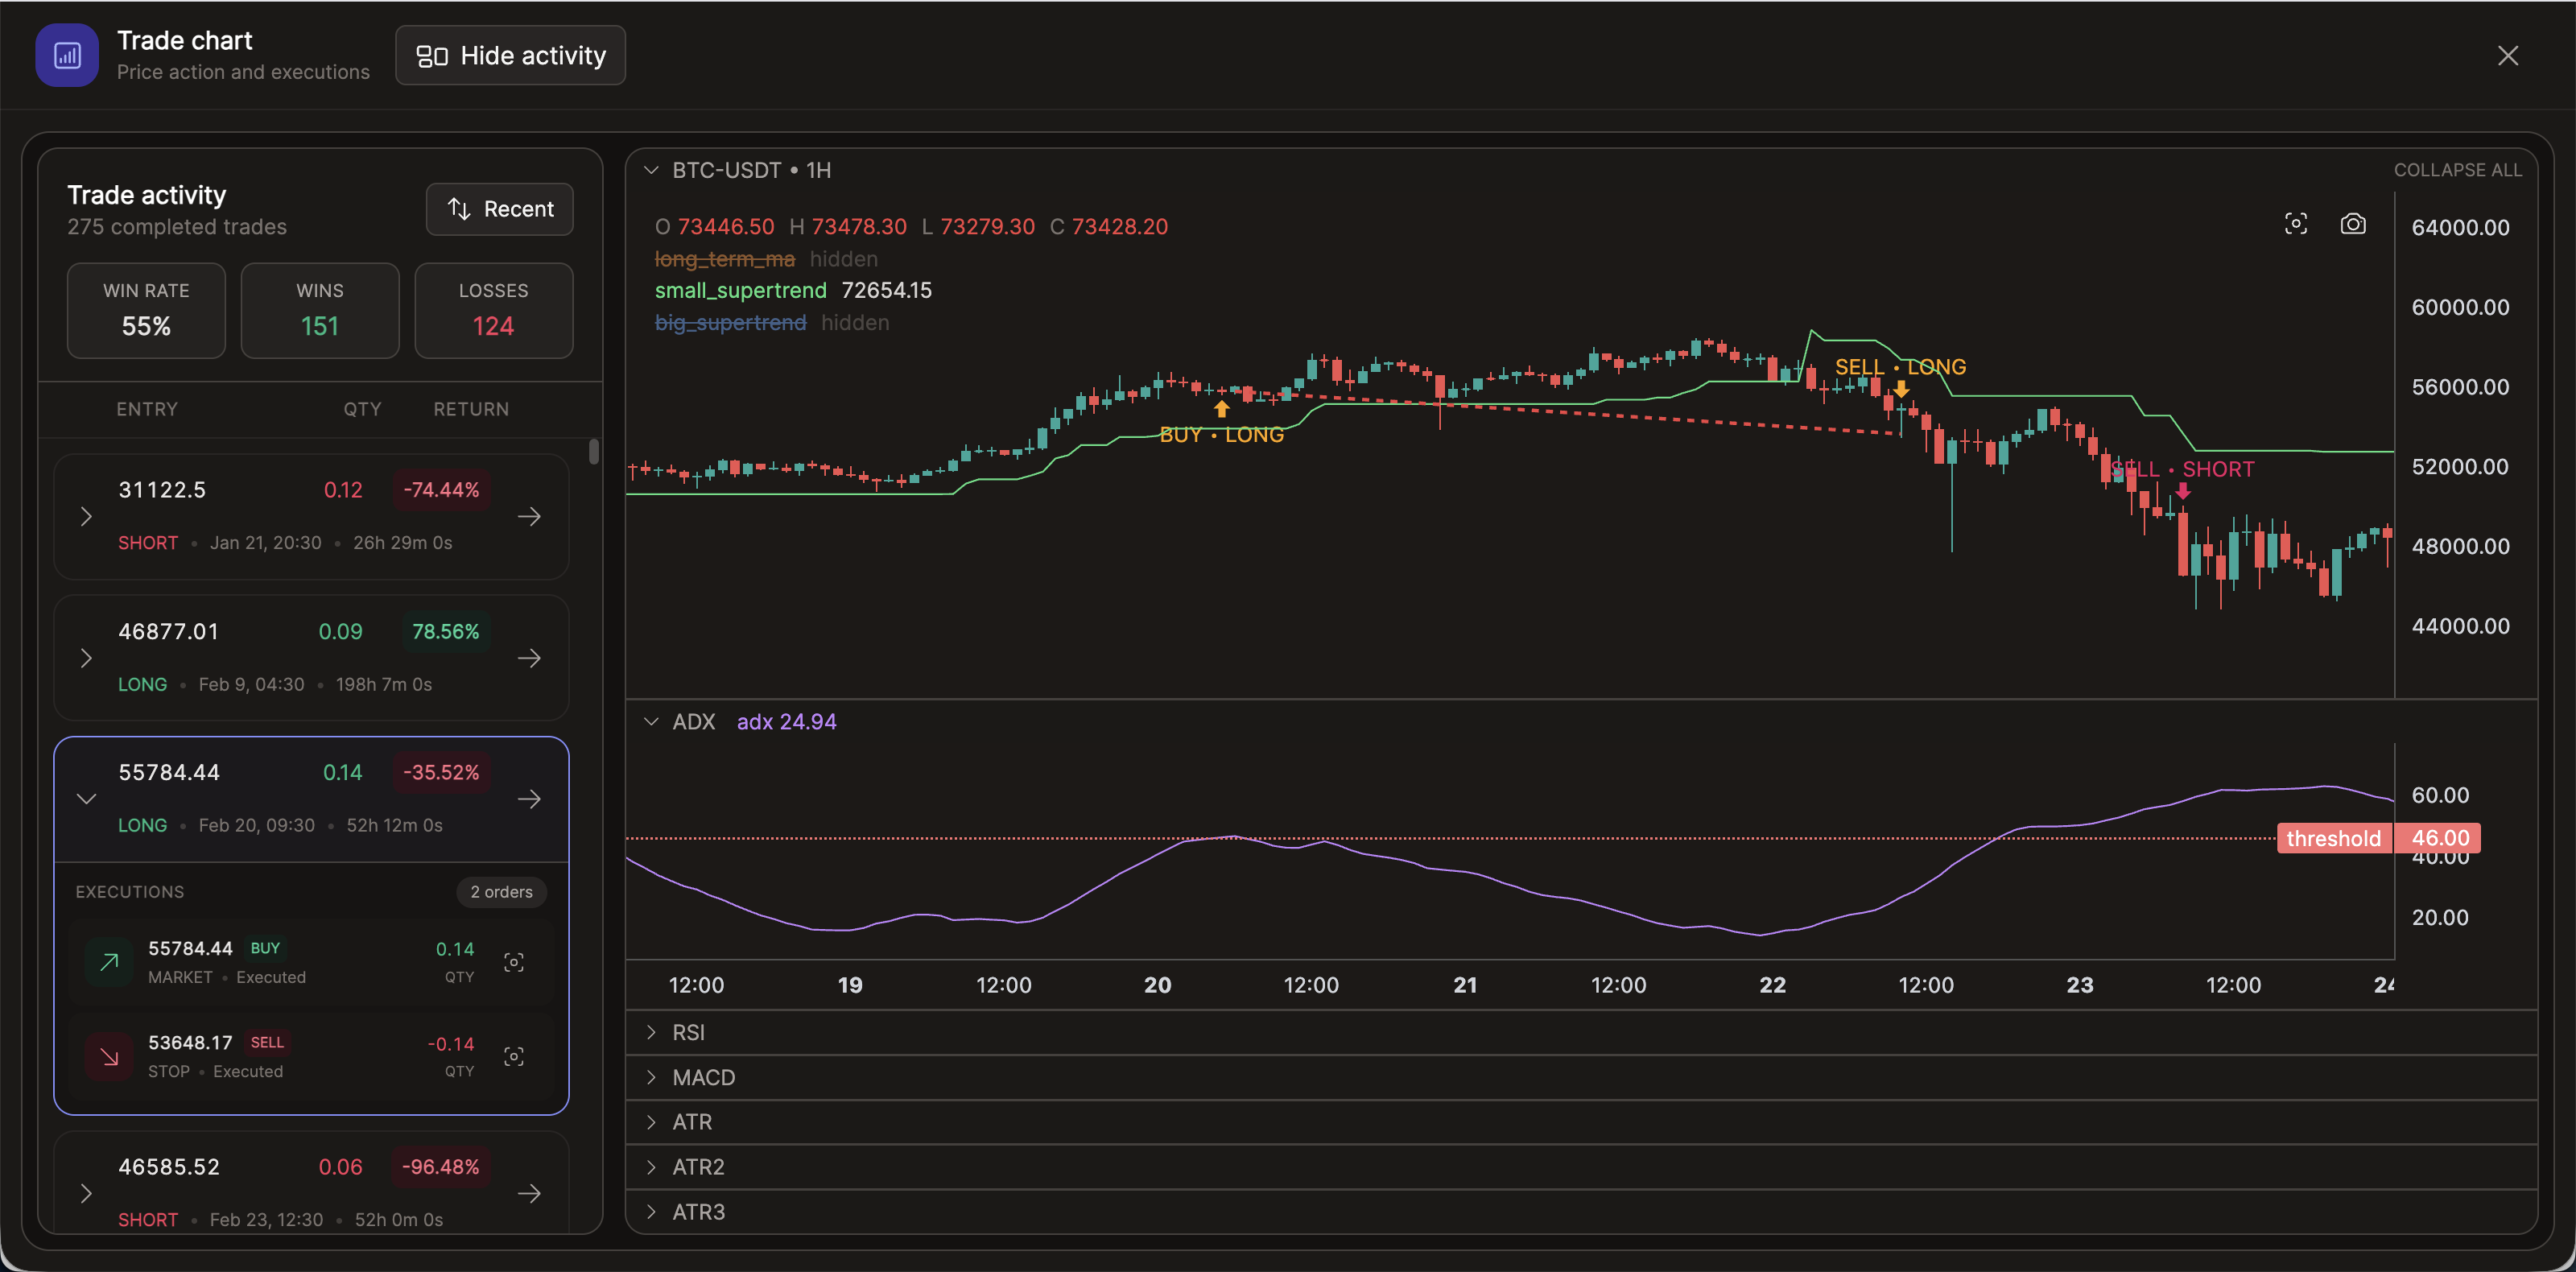
Explore Jesse's interactive charts →
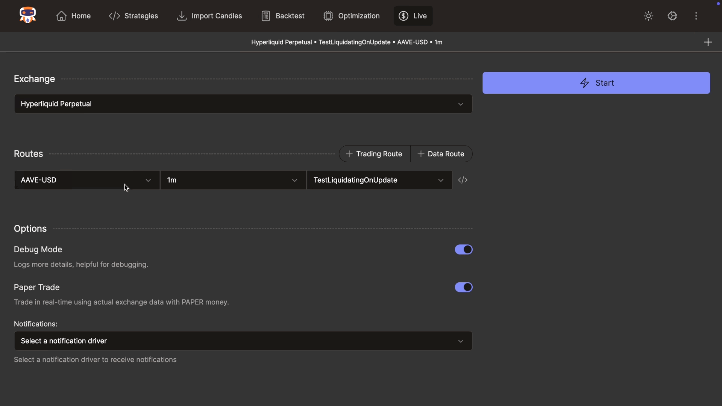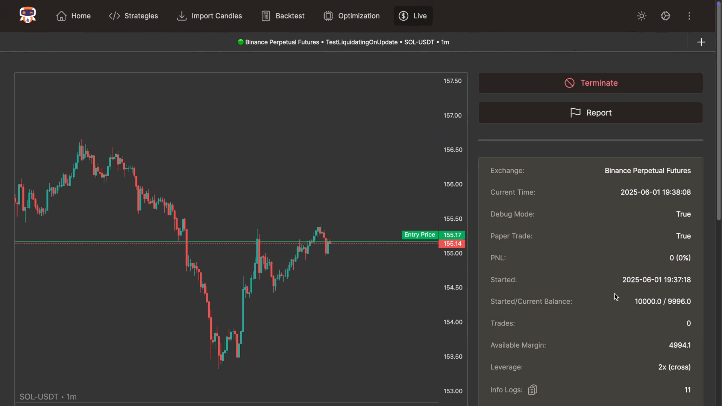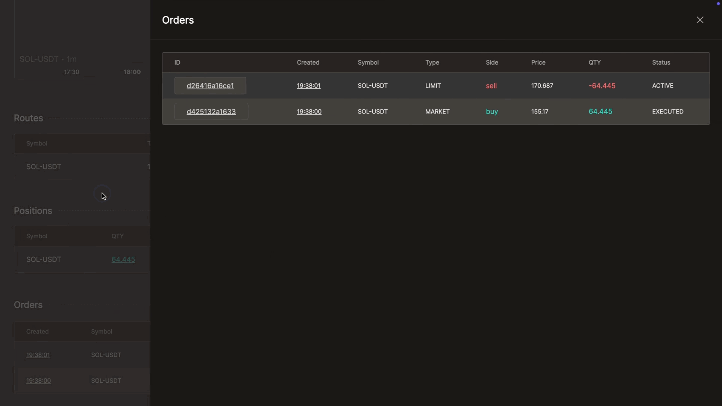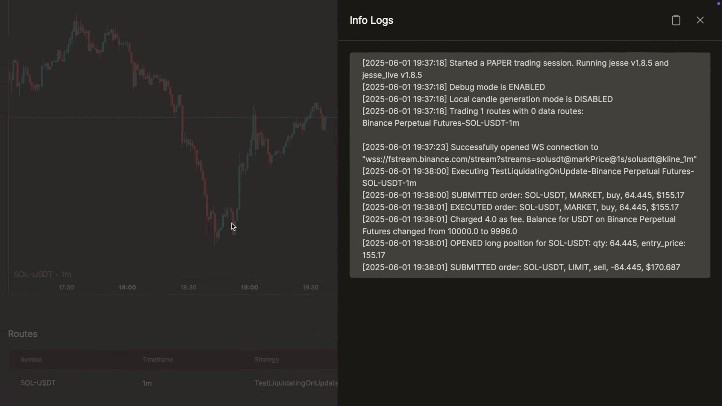
Deploy strategies live with robust monitoring tools. Supports paper trading, multiple accounts, real-time logs & notifications (Telegram, Slack, Discord), interactive charts, spot/futures, DEX, and a built-in code editor.
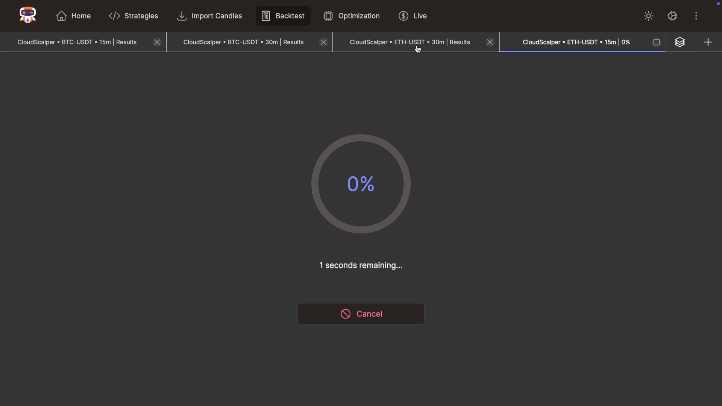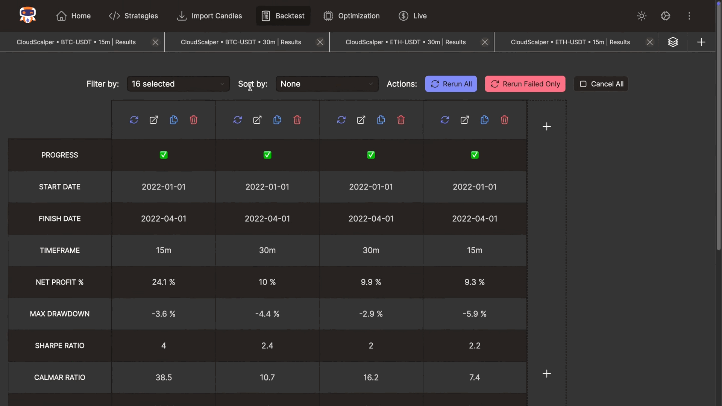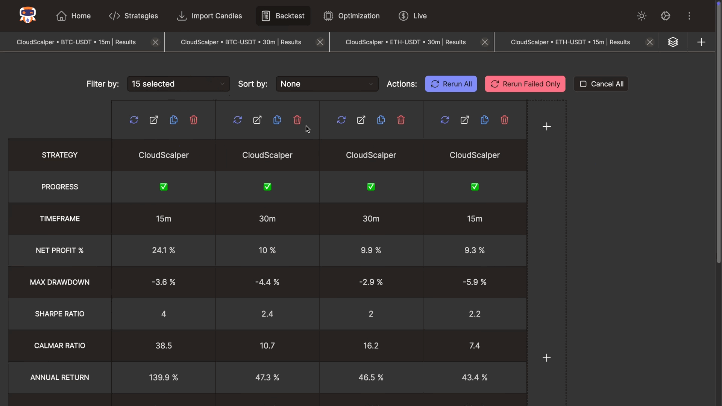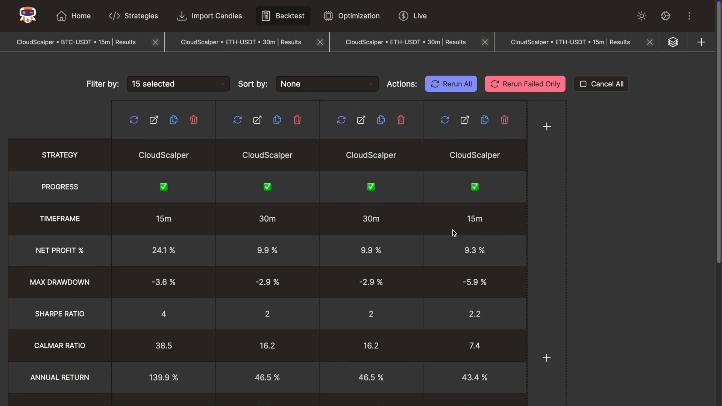
Accelerate research using the benchmark feature. Run batch backtests, compare across timeframes, symbols, and strategies. Filter and sort results by key performance metrics for efficient analysis.
Jesse includes a local Model Context Protocol (MCP) server. Connect your preferred AI assistant and let it work with Jesse's real tools and project context instead of merely guessing how your trading framework behaves.
Through Jesse MCP, an assistant can help you write and improve strategies, manage candle data, run and inspect backtests, perform rule significance tests, optimize parameters, run Monte Carlo simulations, and link you directly to the saved results in the Jesse dashboard. Your strategies and data remain under your control in your self-hosted Jesse setup.
For example, you can ask:
Check whether my new entry rule is statistically significant, backtest it, optimize the promising parameters, and run a candles-based Monte Carlo analysis before we consider paper trading.
Connect Claude, Codex, Cursor, VS Code, or Zed to Jesse →
Before spending hours building and tuning a complete strategy, test whether its entry rule has a measurable historical edge. Jesse compares the rule against a bootstrap distribution of random entries on the same market history, helping you reject noisy ideas early and focus your research on signals worth developing.
Learn about Rule Significance Testing →
Stress-test your strategies beyond a single historical path. Jesse's Monte Carlo mode runs hundreds of simulations using trade-order shuffling (tests whether trade timing drove your results) and candles-based (tests robustness under slightly different market conditions) methods. Use it to distinguish skill from luck, understand the range of outcomes you can realistically expect, and catch overfitting early.
Jesse includes a complete, end-to-end ML pipeline built for trading strategies:
record_features({...}) at each signal bar and record_label(name, value) when the outcome is known. Data is auto-saved to CSV.train_model() with any scikit-learn–compatible estimator and choose a task type: "binary" classification, "multiclass" classification, or "regression". Get a full report with feature importance, calibration, and metrics.ml_predict() or ml_predict_proba() inside your strategy. Model loading, scaling, and feature ordering are handled automatically.# Gather phase — inside your strategy
def before(self):
self.record_features({
'rsi': ta.rsi(self.candles),
'adx': ta.adx(self.candles),
})
# Deploy phase — gate entries with model confidence
def should_long(self):
proba = self.ml_predict_proba()
return proba['long'] > 0.65
Explore Jesse's machine-learning pipeline →
Everything does not have to happen through the dashboard. Jesse's Research API exposes candle management, backtesting, optimization, Rule Significance Testing, Monte Carlo analysis, indicators, and machine learning to ordinary Python scripts and Jupyter notebooks. Use it for reproducible experiments, custom reports, batch research, or integration with your existing data-science workflow.
Jesse's indicators are powered by native Rust, making them significantly faster than common alternatives such as TA-Lib.
We are working on first-class reinforcement-learning support built on Jesse's simulation and research stack. The goal is to make training, evaluating, and deploying reinforcement-learning agents feel as integrated as Jesse's existing backtesting, optimization, Monte Carlo, and machine-learning workflows.
Unsure about optimal parameters? Let the optimization mode decide using simple syntax. Fine-tune any strategy parameter with the Optuna library and easy cross-validation.
@property
def slow_sma(self):
    return ta.sma(self.candles, self.hp['slow_sma_period'])

@property
def fast_sma(self):
    return ta.sma(self.candles, self.hp['fast_sma_period'])

def hyperparameters(self):
    return [
        {'name': 'slow_sma_period', 'type': int, 'min': 150, 'max': 210, 'default': 200},
        {'name': 'fast_sma_period', 'type': int, 'min': 20, 'max': 100, 'default': 50},
    ]
Head over to the "getting started" section of the documentation. The documentation is short yet very informative.
You can see the project's roadmap here. Subscribe to our mailing list at jesse.trade to get the good stuff as soon they're released. Don't worry, We won't send you spam—Pinky promise.
This software is for educational purposes only. USE THE SOFTWARE AT YOUR OWN RISK. THE AUTHORS AND ALL AFFILIATES ASSUME NO RESPONSIBILITY FOR YOUR TRADING RESULTS. Do not risk money that you are afraid to lose. There might be bugs in the code - this software DOES NOT come with ANY warranty.
Overall
Maintained
Code review
PyPI
Latest release
Releases this year
(top 24 of 34)
305 followers · starred Mar 2025
148 followers · starred Jun 2021
34 followers · starred Jan 2021
224 followers · starred Mar 2021
An advanced crypto trading bot written in Python
See the code
Algo-trading was 😵💫, we made it 🤩
Jesse is an advanced crypto trading framework that aims to simplify researching and defining YOUR OWN trading strategies for backtesting, optimizing, and live trading.
Watch this video to get a quick overview of Jesse:
In short, Jesse is more accurate than other solutions, and way more simple. In fact, it is so simple that in case you already know Python, you can get started today, in matter of minutes, instead of weeks and months.
Craft complex trading strategies with remarkably simple Python. Access 300+ indicators, multi-symbol/timeframe support, spot/futures trading, partial fills, and risk management tools. Focus on logic, not boilerplate.
class GoldenCross(Strategy):
    def should_long(self):
        # go long when the EMA 8 is above the EMA 21
        short_ema = ta.ema(self.candles, 8)
        long_ema = ta.ema(self.candles, 21)
        return short_ema > long_ema

    def go_long(self):
        entry_price = self.price - 10        # limit buy order at $10 below the current price
        qty = utils.size_to_qty(self.balance*0.05, entry_price) # spend only 5% of my total capital
        self.buy = qty, entry_price                 # submit entry order
        self.take_profit = qty, entry_price*1.2  # take profit at 20% above the entry price
        self.stop_loss = qty, entry_price*0.9   # stop loss at 10% below the entry price
Execute highly accurate and fast backtests without look-ahead bias. Utilize debugging logs, interactive charts with indicator support, and detailed performance metrics to validate your strategies thoroughly.
Inspect your strategy where its decisions happened. Jesse combines candlesticks, strategy-added indicators and levels, executed orders, and completed trades in synchronized interactive charts. The same charting workflow is available for backtests and for running or completed paper/live sessions.
Expand a trade to inspect every execution, collapse or isolate indicator panes, follow OHLC and indicator values under the cursor, reset the view, use fullscreen mode, or export the chart as an image.
Explore Jesse's interactive charts →
Deploy strategies live with robust monitoring tools. Supports paper trading, multiple accounts, real-time logs & notifications (Telegram, Slack, Discord), interactive charts, spot/futures, DEX, and a built-in code editor.
Accelerate research using the benchmark feature. Run batch backtests, compare across timeframes, symbols, and strategies. Filter and sort results by key performance metrics for efficient analysis.
Jesse includes a local Model Context Protocol (MCP) server. Connect your preferred AI assistant and let it work with Jesse's real tools and project context instead of merely guessing how your trading framework behaves.
Through Jesse MCP, an assistant can help you write and improve strategies, manage candle data, run and inspect backtests, perform rule significance tests, optimize parameters, run Monte Carlo simulations, and link you directly to the saved results in the Jesse dashboard. Your strategies and data remain under your control in your self-hosted Jesse setup.
For example, you can ask:
Check whether my new entry rule is statistically significant, backtest it, optimize the promising parameters, and run a candles-based Monte Carlo analysis before we consider paper trading.
Connect Claude, Codex, Cursor, VS Code, or Zed to Jesse →
Before spending hours building and tuning a complete strategy, test whether its entry rule has a measurable historical edge. Jesse compares the rule against a bootstrap distribution of random entries on the same market history, helping you reject noisy ideas early and focus your research on signals worth developing.
Learn about Rule Significance Testing →
Stress-test your strategies beyond a single historical path. Jesse's Monte Carlo mode runs hundreds of simulations using trade-order shuffling (tests whether trade timing drove your results) and candles-based (tests robustness under slightly different market conditions) methods. Use it to distinguish skill from luck, understand the range of outcomes you can realistically expect, and catch overfitting early.
Jesse includes a complete, end-to-end ML pipeline built for trading strategies:
record_features({...}) at each signal bar and record_label(name, value) when the outcome is known. Data is auto-saved to CSV.train_model() with any scikit-learn–compatible estimator and choose a task type: "binary" classification, "multiclass" classification, or "regression". Get a full report with feature importance, calibration, and metrics.ml_predict() or ml_predict_proba() inside your strategy. Model loading, scaling, and feature ordering are handled automatically.# Gather phase — inside your strategy
def before(self):
self.record_features({
'rsi': ta.rsi(self.candles),
'adx': ta.adx(self.candles),
})
# Deploy phase — gate entries with model confidence
def should_long(self):
proba = self.ml_predict_proba()
return proba['long'] > 0.65
Explore Jesse's machine-learning pipeline →
Everything does not have to happen through the dashboard. Jesse's Research API exposes candle management, backtesting, optimization, Rule Significance Testing, Monte Carlo analysis, indicators, and machine learning to ordinary Python scripts and Jupyter notebooks. Use it for reproducible experiments, custom reports, batch research, or integration with your existing data-science workflow.
Jesse's indicators are powered by native Rust, making them significantly faster than common alternatives such as TA-Lib.
We are working on first-class reinforcement-learning support built on Jesse's simulation and research stack. The goal is to make training, evaluating, and deploying reinforcement-learning agents feel as integrated as Jesse's existing backtesting, optimization, Monte Carlo, and machine-learning workflows.
Unsure about optimal parameters? Let the optimization mode decide using simple syntax. Fine-tune any strategy parameter with the Optuna library and easy cross-validation.
@property
def slow_sma(self):
    return ta.sma(self.candles, self.hp['slow_sma_period'])

@property
def fast_sma(self):
    return ta.sma(self.candles, self.hp['fast_sma_period'])

def hyperparameters(self):
    return [
        {'name': 'slow_sma_period', 'type': int, 'min': 150, 'max': 210, 'default': 200},
        {'name': 'fast_sma_period', 'type': int, 'min': 20, 'max': 100, 'default': 50},
    ]
Head over to the "getting started" section of the documentation. The documentation is short yet very informative.
You can see the project's roadmap here. Subscribe to our mailing list at jesse.trade to get the good stuff as soon they're released. Don't worry, We won't send you spam—Pinky promise.
This software is for educational purposes only. USE THE SOFTWARE AT YOUR OWN RISK. THE AUTHORS AND ALL AFFILIATES ASSUME NO RESPONSIBILITY FOR YOUR TRADING RESULTS. Do not risk money that you are afraid to lose. There might be bugs in the code - this software DOES NOT come with ANY warranty.
Overall
Maintained
Code review
PyPI
Latest release
Releases this year
(top 24 of 34)
305 followers · starred Mar 2025
148 followers · starred Jun 2021
34 followers · starred Jan 2021
224 followers · starred Mar 2021