Repository for "StockEmotions: Discover Investor Emotions for Financial Sentiment Analysis and Multivariate Time Series" accepted by AAAI 2023 Bridge (AI for Financial Services).
Jupyter Notebook
92
11 commits
updated Feb 7, 2024
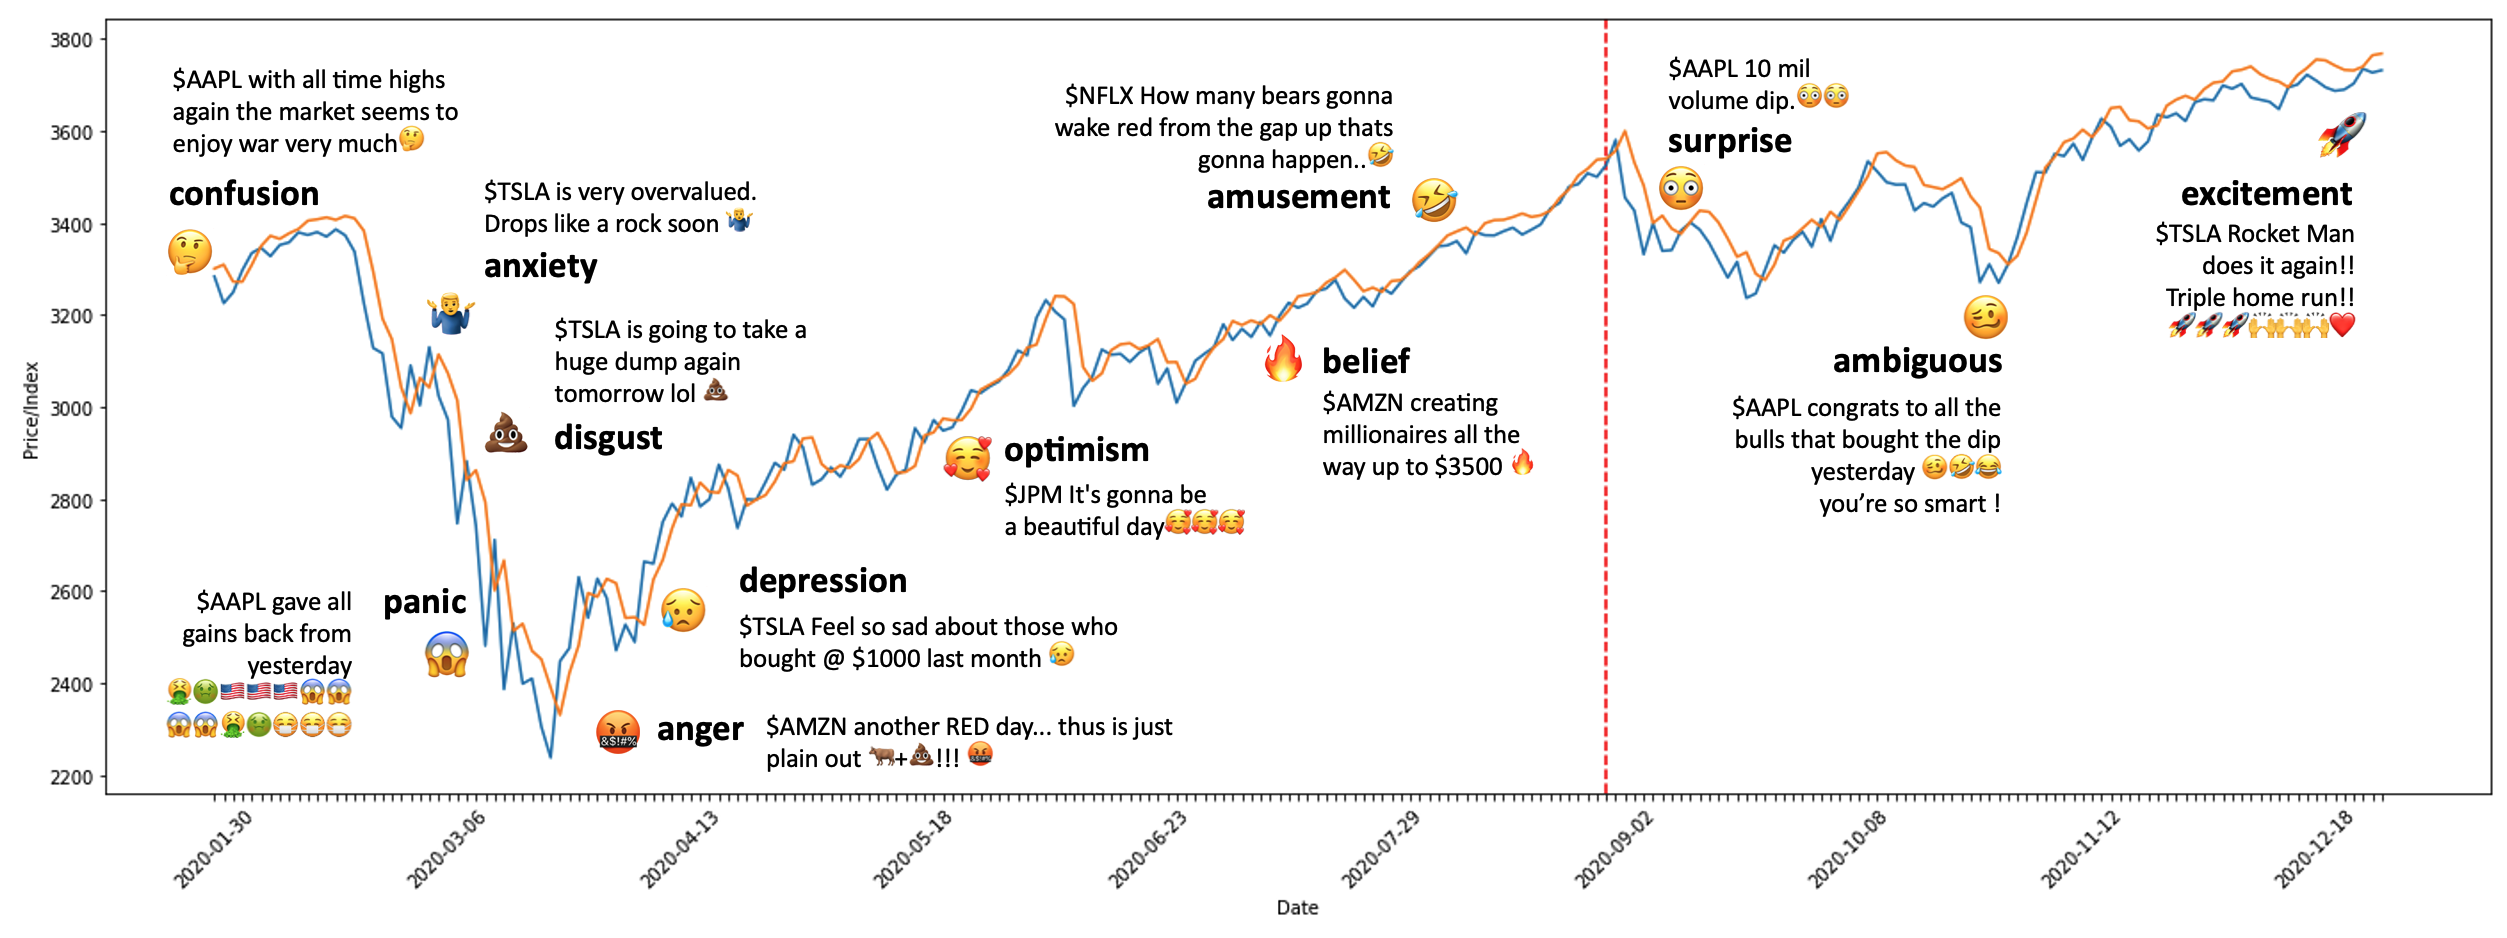
This repository contains a financial-domain-focused dataset for financial sentiment/emotion classification and stock market time series prediction. It's based on our paper: StockEmotions: Discover Investor Emotions for Financial Sentiment Analysis and Multivariate Time Series accepted by AAAI 2023 Bridge (AI for Financial Services).
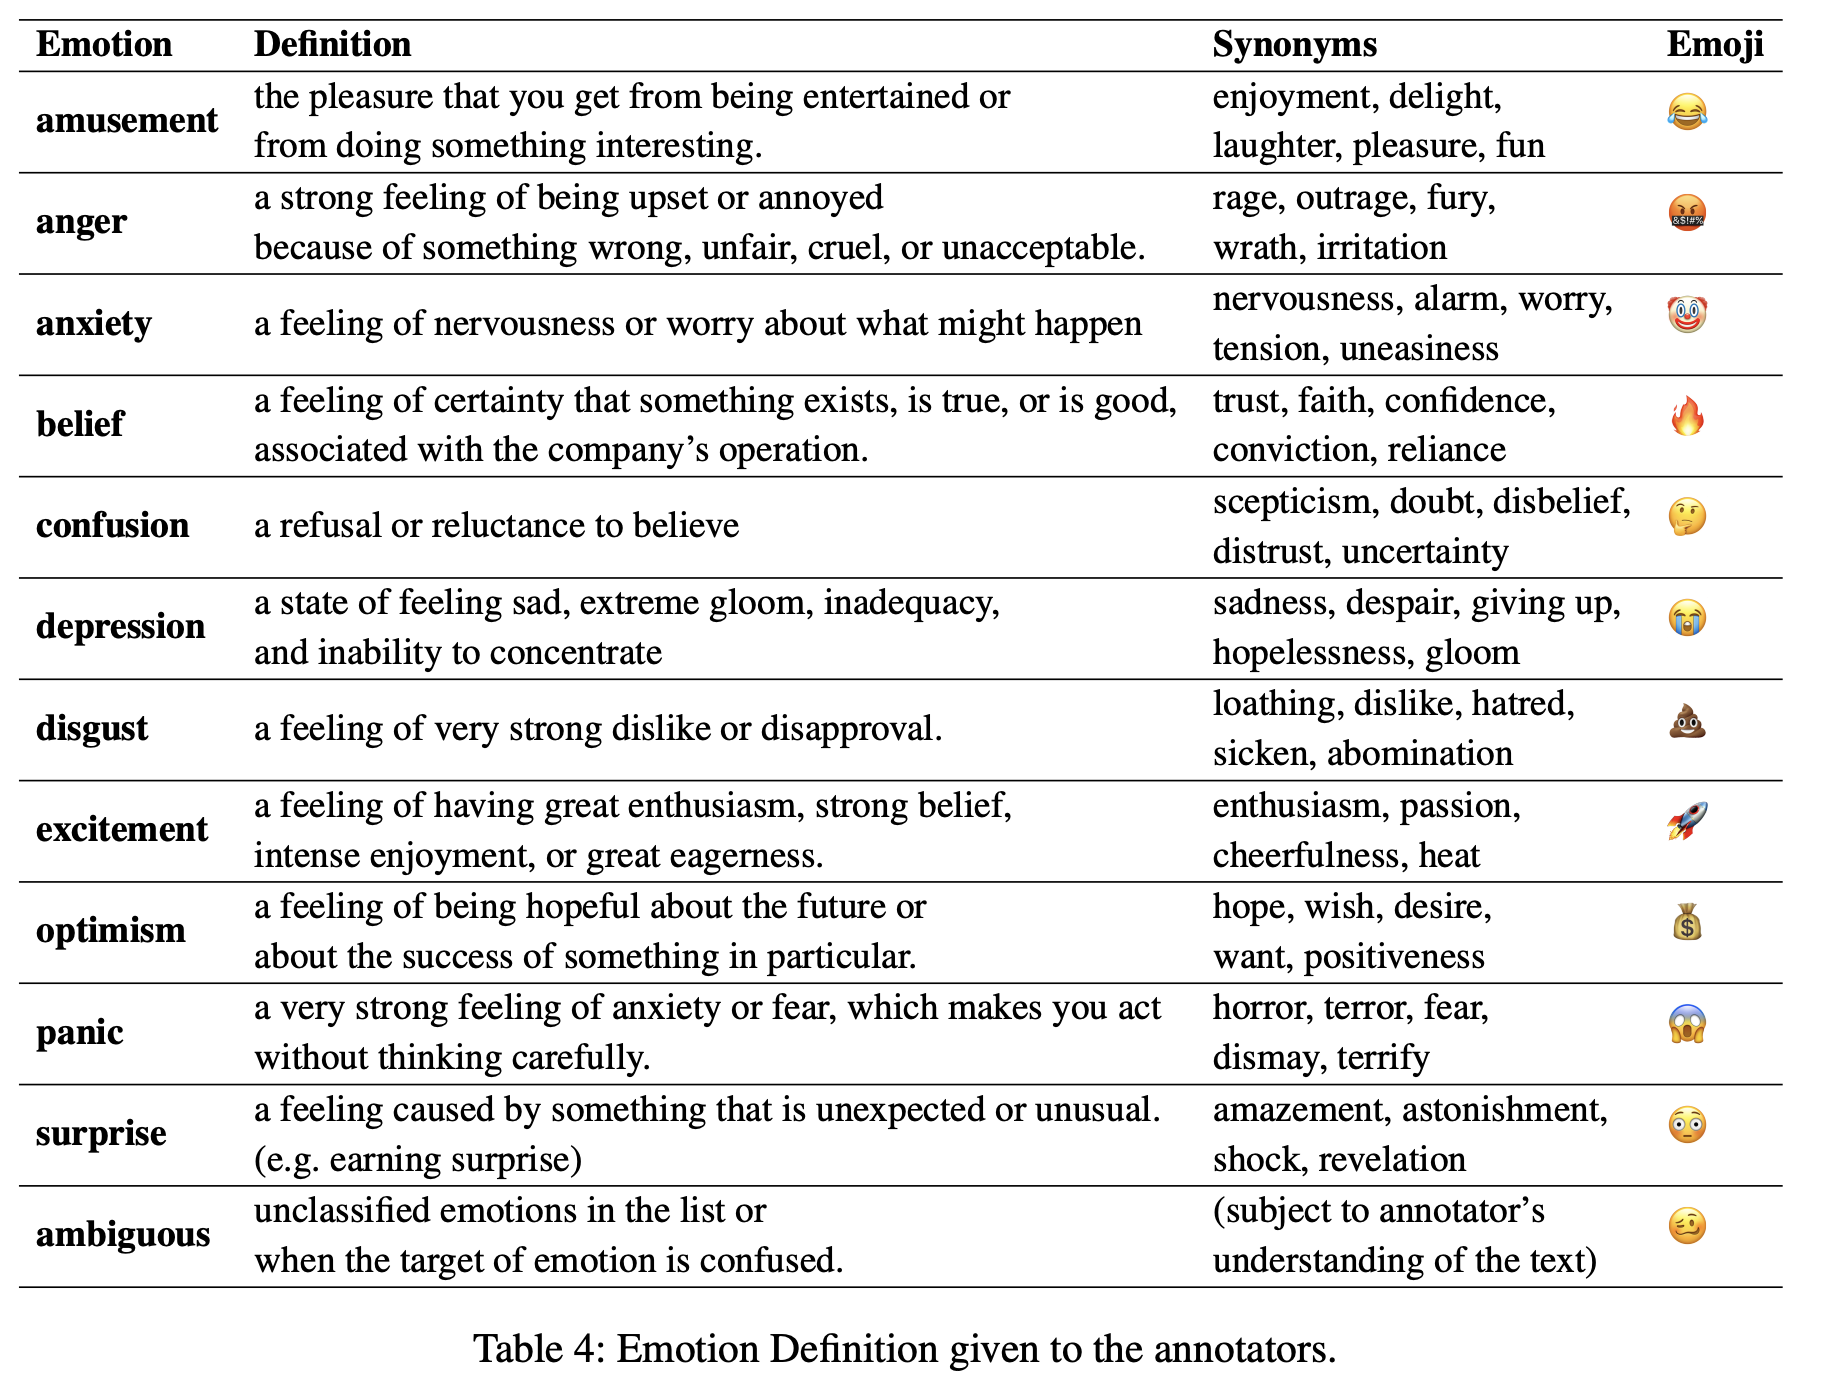

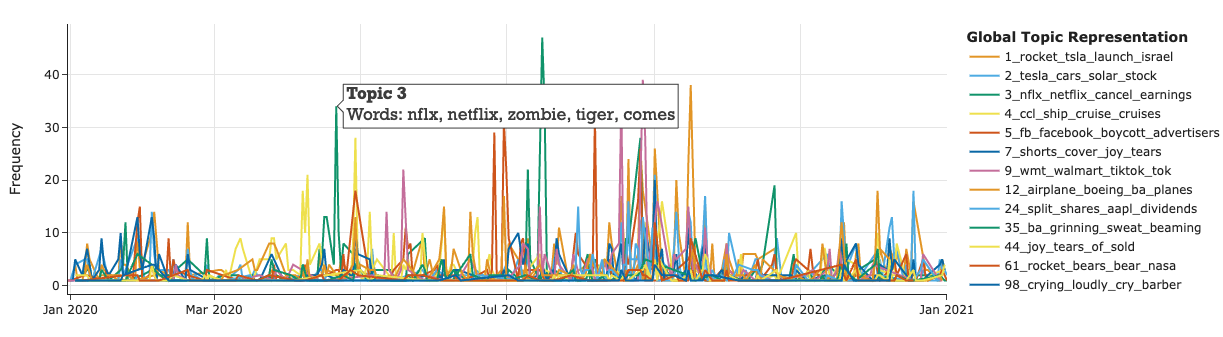
We conduct topic representations using BERTopic to understand whether the curated data represents emotions and to establish the sampling strategy for annotation.
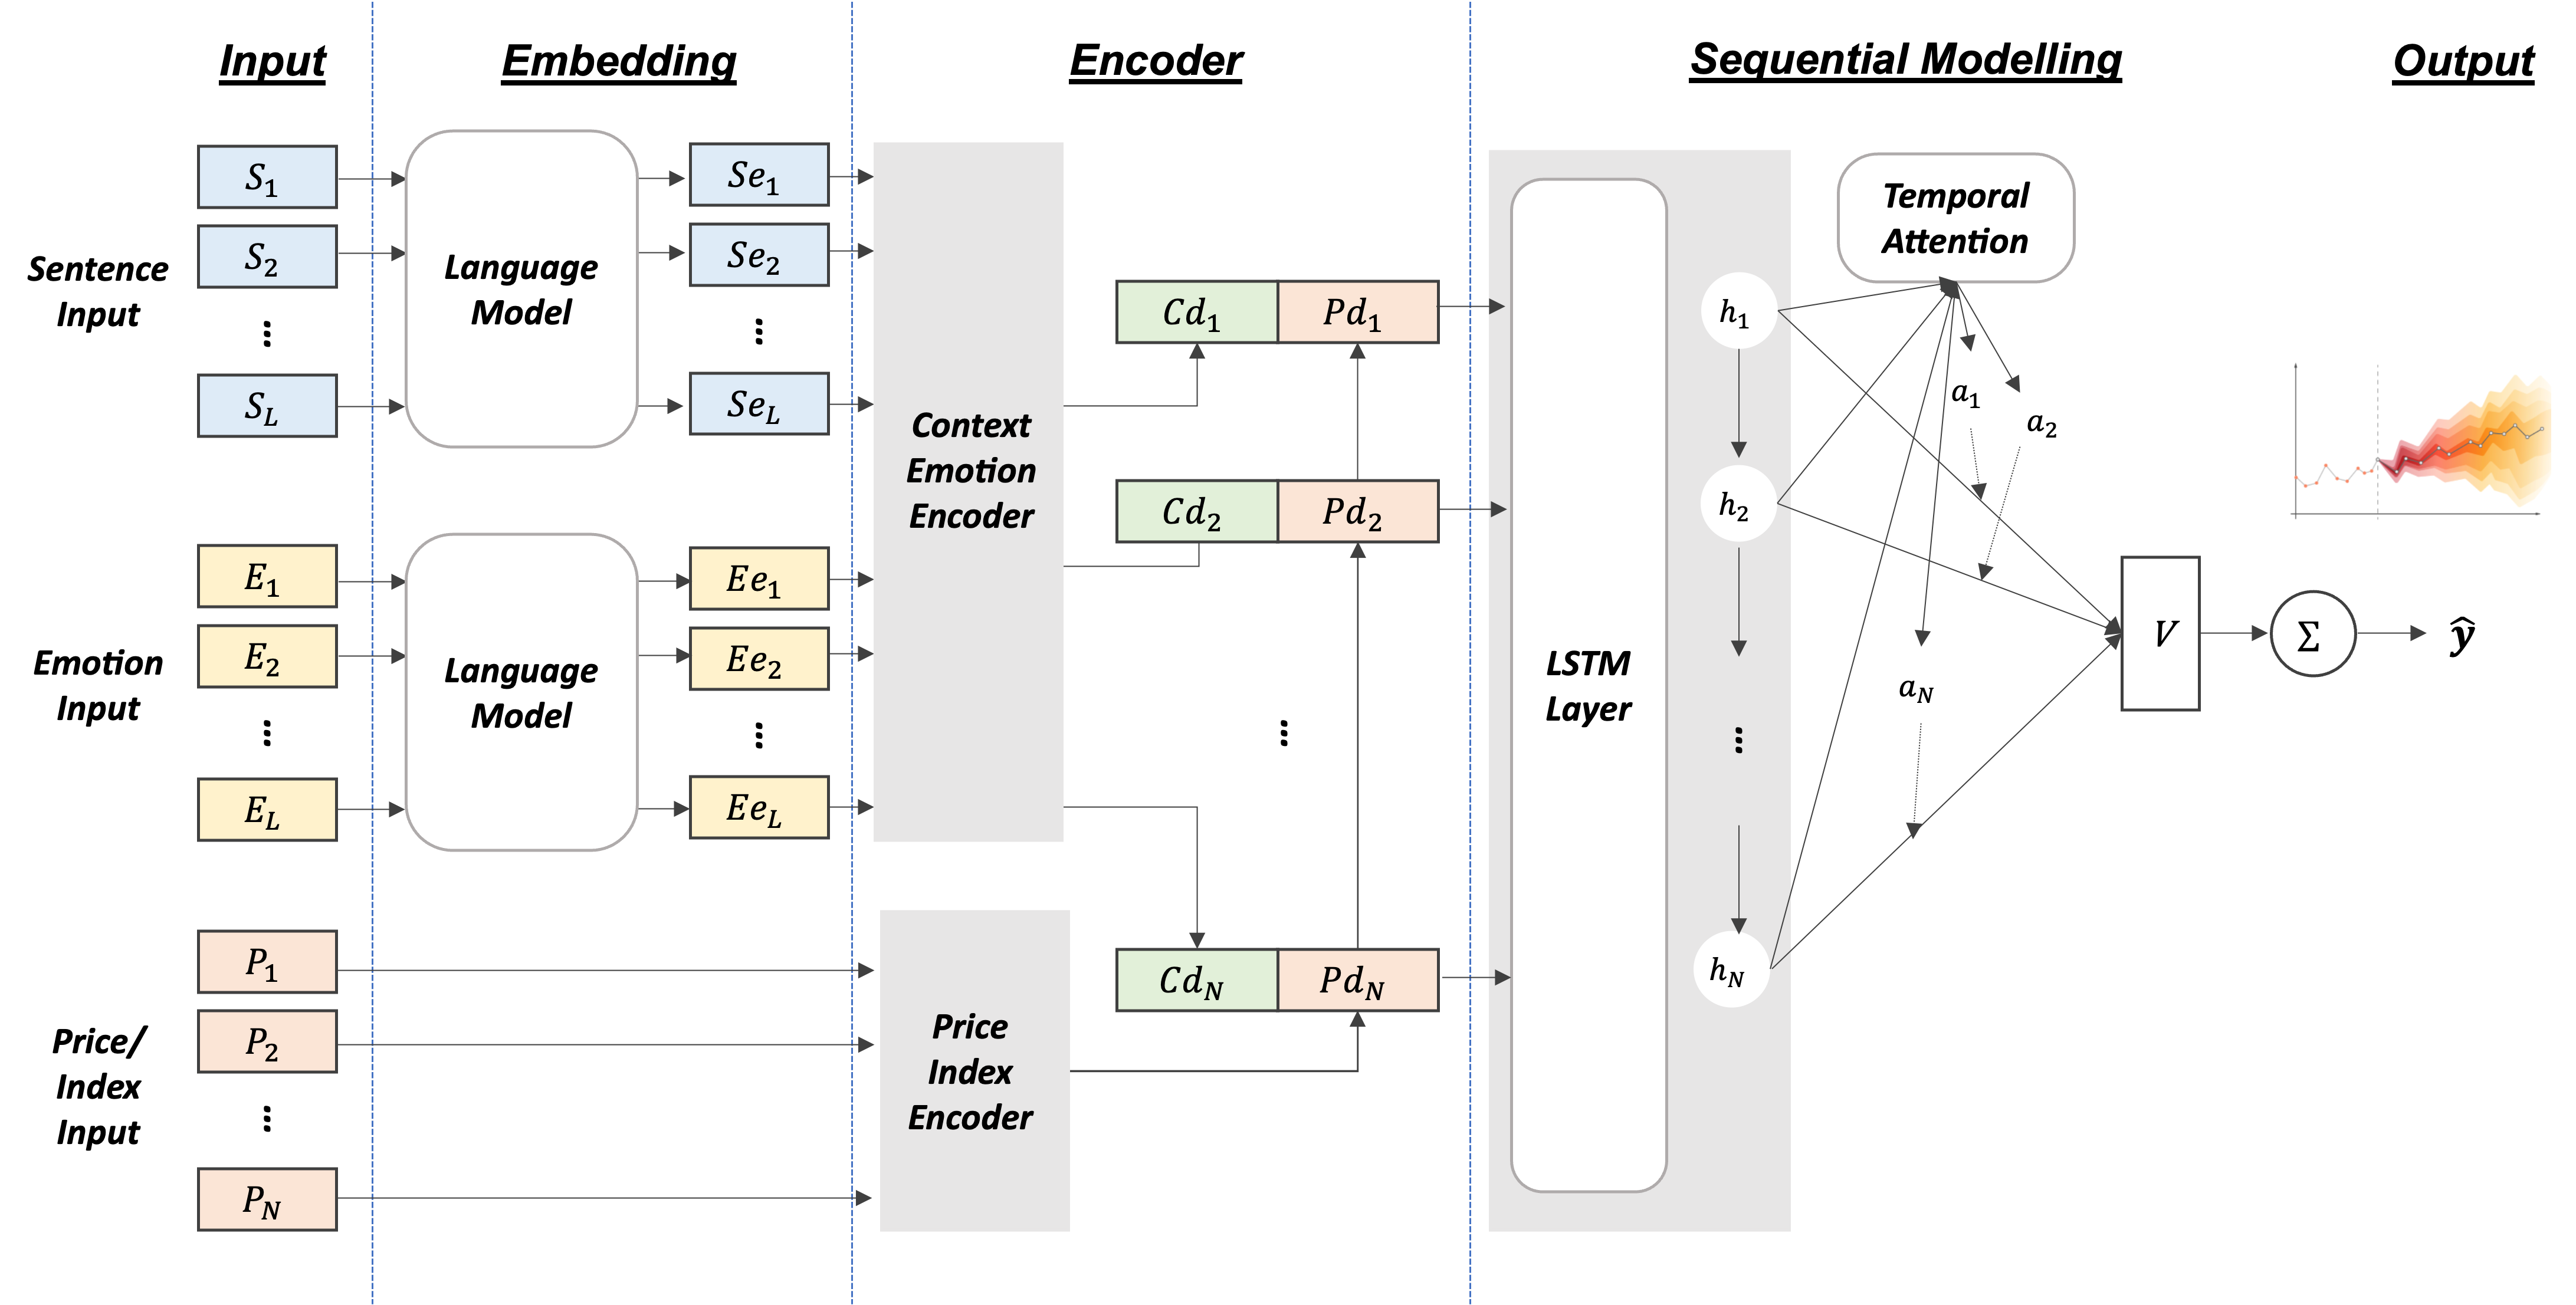
We implement a Temporal Attention LSTM with bidirectional encoder representations from transformers (BERT). We will share more experiment results and ablation testing results for further research.
    @article{lee2023stockemotions,
    title={StockEmotions: Discover Investor Emotions for Financial Sentiment Analysis and Multivariate Time Series},
    author={Lee, Jean and Youn, Hoyoul Luis and Poon, Josiah and Han, Soyeon Caren},
    journal={arXiv preprint arXiv:2301.09279},
    year={2023}
    }
Disclaimer: The data collected for this research follows to the terms and conditions of StockTwits and Yahoo Finance. All data included in this research has been anonymized to ensure privacy and confidentiality. If the respective website claims any concerns regarding the data used in this research, we are committed to removing such data from our records. In addition, by using or accessing the information in this repository, you agree to indemnify, defend, and hold harmless the authors, contributors, and any affiliated organizations or persons from any and all claims or damages.
Repository for "StockEmotions: Discover Investor Emotions for Financial Sentiment Analysis and Multivariate Time Series" accepted by AAAI 2023 Bridge (AI for Financial Services).
Jupyter Notebook
92
11 commits
updated Feb 7, 2024
This repository contains a financial-domain-focused dataset for financial sentiment/emotion classification and stock market time series prediction. It's based on our paper: StockEmotions: Discover Investor Emotions for Financial Sentiment Analysis and Multivariate Time Series accepted by AAAI 2023 Bridge (AI for Financial Services).
We conduct topic representations using BERTopic to understand whether the curated data represents emotions and to establish the sampling strategy for annotation.
We implement a Temporal Attention LSTM with bidirectional encoder representations from transformers (BERT). We will share more experiment results and ablation testing results for further research.
    @article{lee2023stockemotions,
    title={StockEmotions: Discover Investor Emotions for Financial Sentiment Analysis and Multivariate Time Series},
    author={Lee, Jean and Youn, Hoyoul Luis and Poon, Josiah and Han, Soyeon Caren},
    journal={arXiv preprint arXiv:2301.09279},
    year={2023}
    }
Disclaimer: The data collected for this research follows to the terms and conditions of StockTwits and Yahoo Finance. All data included in this research has been anonymized to ensure privacy and confidentiality. If the respective website claims any concerns regarding the data used in this research, we are committed to removing such data from our records. In addition, by using or accessing the information in this repository, you agree to indemnify, defend, and hold harmless the authors, contributors, and any affiliated organizations or persons from any and all claims or damages.