Agentic Trading Lab is an open-source experimental platform for LLM-powered trading agents.
Turn trading ideas into traceable experiments: prototype agents, run backtests and paper-trading simulations, inspect reasoning and decision logs, benchmark against market baselines, and study how agents behave under near-real financial constraints.
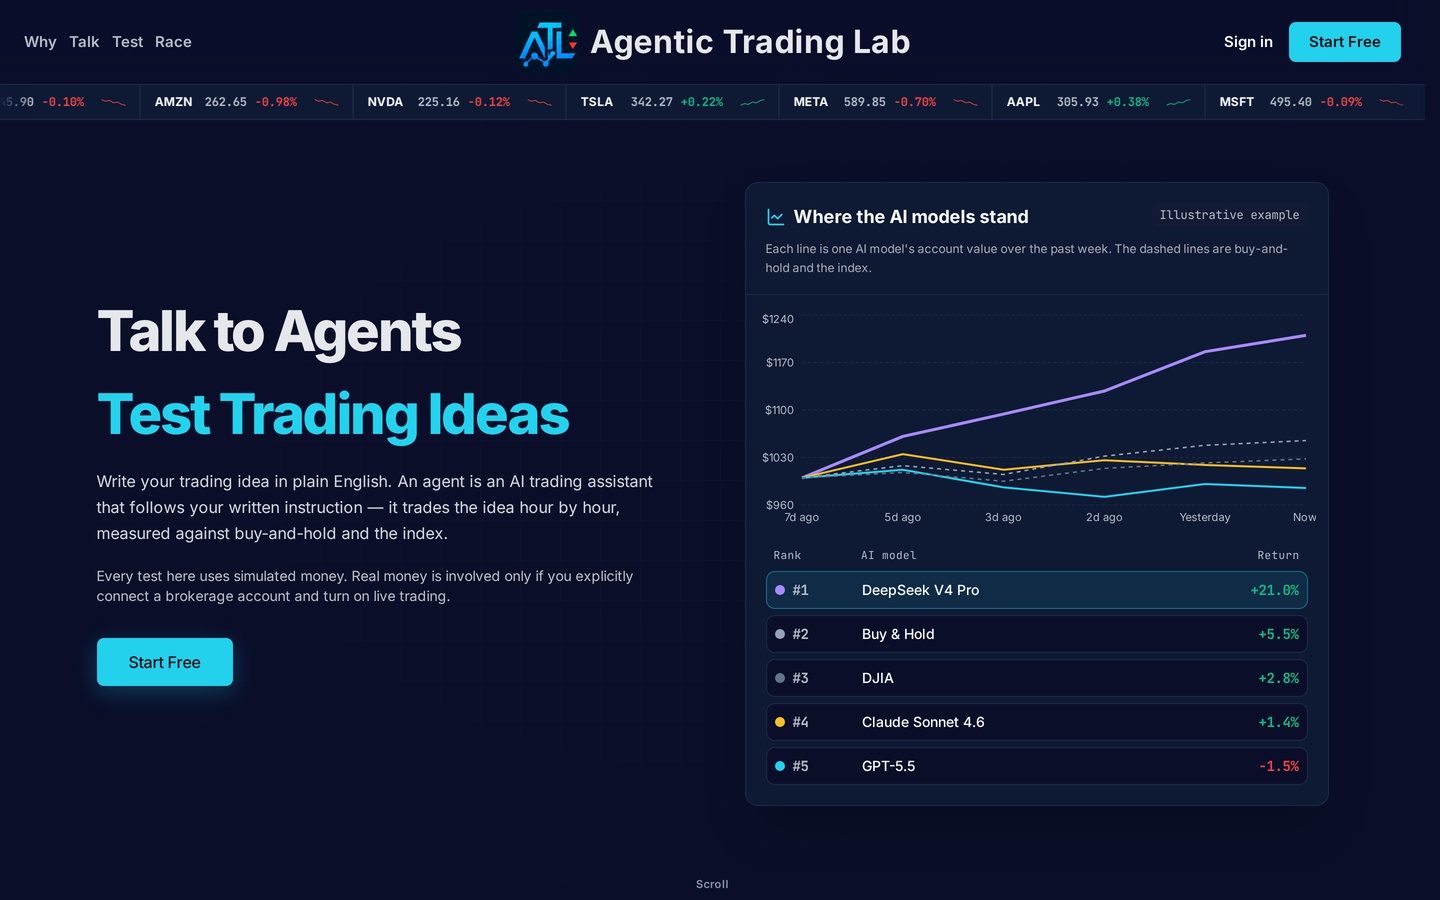
Agentic Trading Lab is an interactive research and educational platform for exploring trading systems powered by large language models. Developed alongside a systematic survey of agentic trading research, it helps students, researchers, and developers explore how agents reason, trade, and perform in realistic market environments. Move beyond backtest returns by customizing agents, inspecting their decisions, evaluating risk, progressing from historical simulation to live-market paper trading, and comparing performance on standardized leaderboards.
Talk to agents. Test trading ideas. Start with a market question or trading idea, then turn it into an agent you can run, observe, and improve.
uv venv --python 3.13 .venv
UV_HTTP_TIMEOUT=180 uv pip install --python .venv/bin/python -r requirements.txt -r requirements-vnpy.txt pytest pytest-timeout
dashboard/scripts/run_local_safe.sh        # http://127.0.0.1:8765/app, no keys, nothing can trade or bill
Full guide (backtests, tests, credentials, troubleshooting): docs/local-run.md.
AgenticTrading/
├── dashboard/                 # Shipping product
│   ├── backend/               # FastAPI package (dashboard.backend.*)
│   │   ├── api/               # /api routers + Agent API v2 (/api/v2)
│   │   ├── domain/            # Business logic (runs, backtesting, leaderboard, trading, …)
│   │   ├── execution/         # v2 execution backends (backtest live; paper stub)
│   │   ├── infrastructure/    # LLM validator, market data, Alpaca + Robinhood brokers
│   │   └── integrations/      # Discord bot, etc.
│   ├── frontend/              # Static assets: landing (/) + dashboard (/app)
│   ├── landing/               # Vite/React landing source (builds into frontend/)
│   ├── scripts/               # CLI backtests (backtest_hourly_agent.py, …)
│   ├── config/                # defaults.json, leaderboard.json, marketplace.json
│   └── storage/               # data/backtest.db + backups/
├── packaging/agentictrading/  # PyPI SDK (AgentRunner + HTTP client)
├── credentials/               # Local only — not in git (see alpaca.json.example)
├── docs/                      # Sphinx docs + architecture notes
├── orchestration/             # FinAgent multi-agent framework (separate)
├── requirements.txt           # Dashboard deps (not root pyproject.toml)
├── Dockerfile / render.yaml   # Backend deploy
└── dashboard/frontend/vercel.json  # Frontend static deploy (must sit in the Vercel Root Directory)
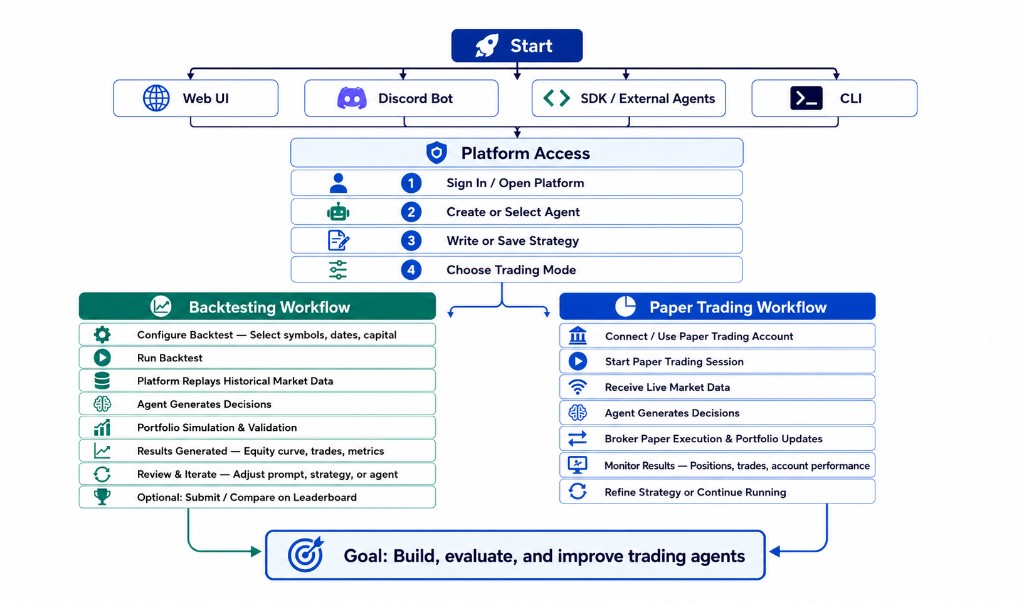
Agentic Trading Lab is evolving from an experimental playground into an open platform where trading agents, models, data, and tools can be connected, managed, evaluated, and reused.
Progress so far: news sentiment is live via Agentic FinSearch (Home panel + v2 agent context), with Reddit/social sentiment still planned. Under Broader agent and tool connectivity, the first external-framework adapter has shipped — TradingAgents runs locally on your own model and data credentials and replays its decisions through the Python SDK (setup guide, written in Simplified Chinese) — while MCP, broker, and data-provider adapters are still ahead.
This repository includes the FinAgent Orchestration Framework under orchestration/, developed by Jifeng Li et al. at Open Finance Lab. The orchestration framework provides multi-agent architecture, memory systems, and DAG-based planning components. See orchestration/README.md for details.
If you use the orchestration framework in research, please cite:
@inproceedings{orchestration_finagents_2025,
   title     = {Orchestration Framework for Financial Agents: From Algorithmic Trading to Agentic Trading},
   author    = {Jifeng Li and Arnav Grover and Abraham Alpuerto and Yupeng Cao and Xiao-Yang Liu},
   booktitle = {NeurIPS 2025 Workshop on Generative AI in Finance},
   year      = {2025},
}
Plain-text citation:
Jifeng Li, Arnav Grover, Abraham Alpuerto, Yupeng Cao, and Xiao-Yang Liu. Orchestration Framework for Financial Agents: From Algorithmic Trading to Agentic Trading. NeurIPS 2025 Workshop on Generative AI in Finance, 2025.
Documentation: finagent-orchestration.readthedocs.io. Local preview: docs/README.md
OpenMDW-1.0 — See LICENSE (Copyright @ SecureFinAI Lab)
Pull requests and issues welcome!
Built with Alpaca API, FastAPI, Chart.js, and SQLite
67 followers · starred Jul 2026
33 followers · starred Jun 2026
Agentic Trading Lab is an open-source experimental platform for LLM-powered trading agents.
Turn trading ideas into traceable experiments: prototype agents, run backtests and paper-trading simulations, inspect reasoning and decision logs, benchmark against market baselines, and study how agents behave under near-real financial constraints.
Agentic Trading Lab is an interactive research and educational platform for exploring trading systems powered by large language models. Developed alongside a systematic survey of agentic trading research, it helps students, researchers, and developers explore how agents reason, trade, and perform in realistic market environments. Move beyond backtest returns by customizing agents, inspecting their decisions, evaluating risk, progressing from historical simulation to live-market paper trading, and comparing performance on standardized leaderboards.
Talk to agents. Test trading ideas. Start with a market question or trading idea, then turn it into an agent you can run, observe, and improve.
uv venv --python 3.13 .venv
UV_HTTP_TIMEOUT=180 uv pip install --python .venv/bin/python -r requirements.txt -r requirements-vnpy.txt pytest pytest-timeout
dashboard/scripts/run_local_safe.sh        # http://127.0.0.1:8765/app, no keys, nothing can trade or bill
Full guide (backtests, tests, credentials, troubleshooting): docs/local-run.md.
AgenticTrading/
├── dashboard/                 # Shipping product
│   ├── backend/               # FastAPI package (dashboard.backend.*)
│   │   ├── api/               # /api routers + Agent API v2 (/api/v2)
│   │   ├── domain/            # Business logic (runs, backtesting, leaderboard, trading, …)
│   │   ├── execution/         # v2 execution backends (backtest live; paper stub)
│   │   ├── infrastructure/    # LLM validator, market data, Alpaca + Robinhood brokers
│   │   └── integrations/      # Discord bot, etc.
│   ├── frontend/              # Static assets: landing (/) + dashboard (/app)
│   ├── landing/               # Vite/React landing source (builds into frontend/)
│   ├── scripts/               # CLI backtests (backtest_hourly_agent.py, …)
│   ├── config/                # defaults.json, leaderboard.json, marketplace.json
│   └── storage/               # data/backtest.db + backups/
├── packaging/agentictrading/  # PyPI SDK (AgentRunner + HTTP client)
├── credentials/               # Local only — not in git (see alpaca.json.example)
├── docs/                      # Sphinx docs + architecture notes
├── orchestration/             # FinAgent multi-agent framework (separate)
├── requirements.txt           # Dashboard deps (not root pyproject.toml)
├── Dockerfile / render.yaml   # Backend deploy
└── dashboard/frontend/vercel.json  # Frontend static deploy (must sit in the Vercel Root Directory)
Agentic Trading Lab is evolving from an experimental playground into an open platform where trading agents, models, data, and tools can be connected, managed, evaluated, and reused.
Progress so far: news sentiment is live via Agentic FinSearch (Home panel + v2 agent context), with Reddit/social sentiment still planned. Under Broader agent and tool connectivity, the first external-framework adapter has shipped — TradingAgents runs locally on your own model and data credentials and replays its decisions through the Python SDK (setup guide, written in Simplified Chinese) — while MCP, broker, and data-provider adapters are still ahead.
This repository includes the FinAgent Orchestration Framework under orchestration/, developed by Jifeng Li et al. at Open Finance Lab. The orchestration framework provides multi-agent architecture, memory systems, and DAG-based planning components. See orchestration/README.md for details.
If you use the orchestration framework in research, please cite:
@inproceedings{orchestration_finagents_2025,
   title     = {Orchestration Framework for Financial Agents: From Algorithmic Trading to Agentic Trading},
   author    = {Jifeng Li and Arnav Grover and Abraham Alpuerto and Yupeng Cao and Xiao-Yang Liu},
   booktitle = {NeurIPS 2025 Workshop on Generative AI in Finance},
   year      = {2025},
}
Plain-text citation:
Jifeng Li, Arnav Grover, Abraham Alpuerto, Yupeng Cao, and Xiao-Yang Liu. Orchestration Framework for Financial Agents: From Algorithmic Trading to Agentic Trading. NeurIPS 2025 Workshop on Generative AI in Finance, 2025.
Documentation: finagent-orchestration.readthedocs.io. Local preview: docs/README.md
OpenMDW-1.0 — See LICENSE (Copyright @ SecureFinAI Lab)
Pull requests and issues welcome!
Built with Alpaca API, FastAPI, Chart.js, and SQLite
67 followers · starred Jul 2026
33 followers · starred Jun 2026



