[NeurIPS 2025 & ICLR 2025 Financial AI Best Paper Award] A multi-agent framework that leverages LLMs to simulate socio-economic systems
See the code


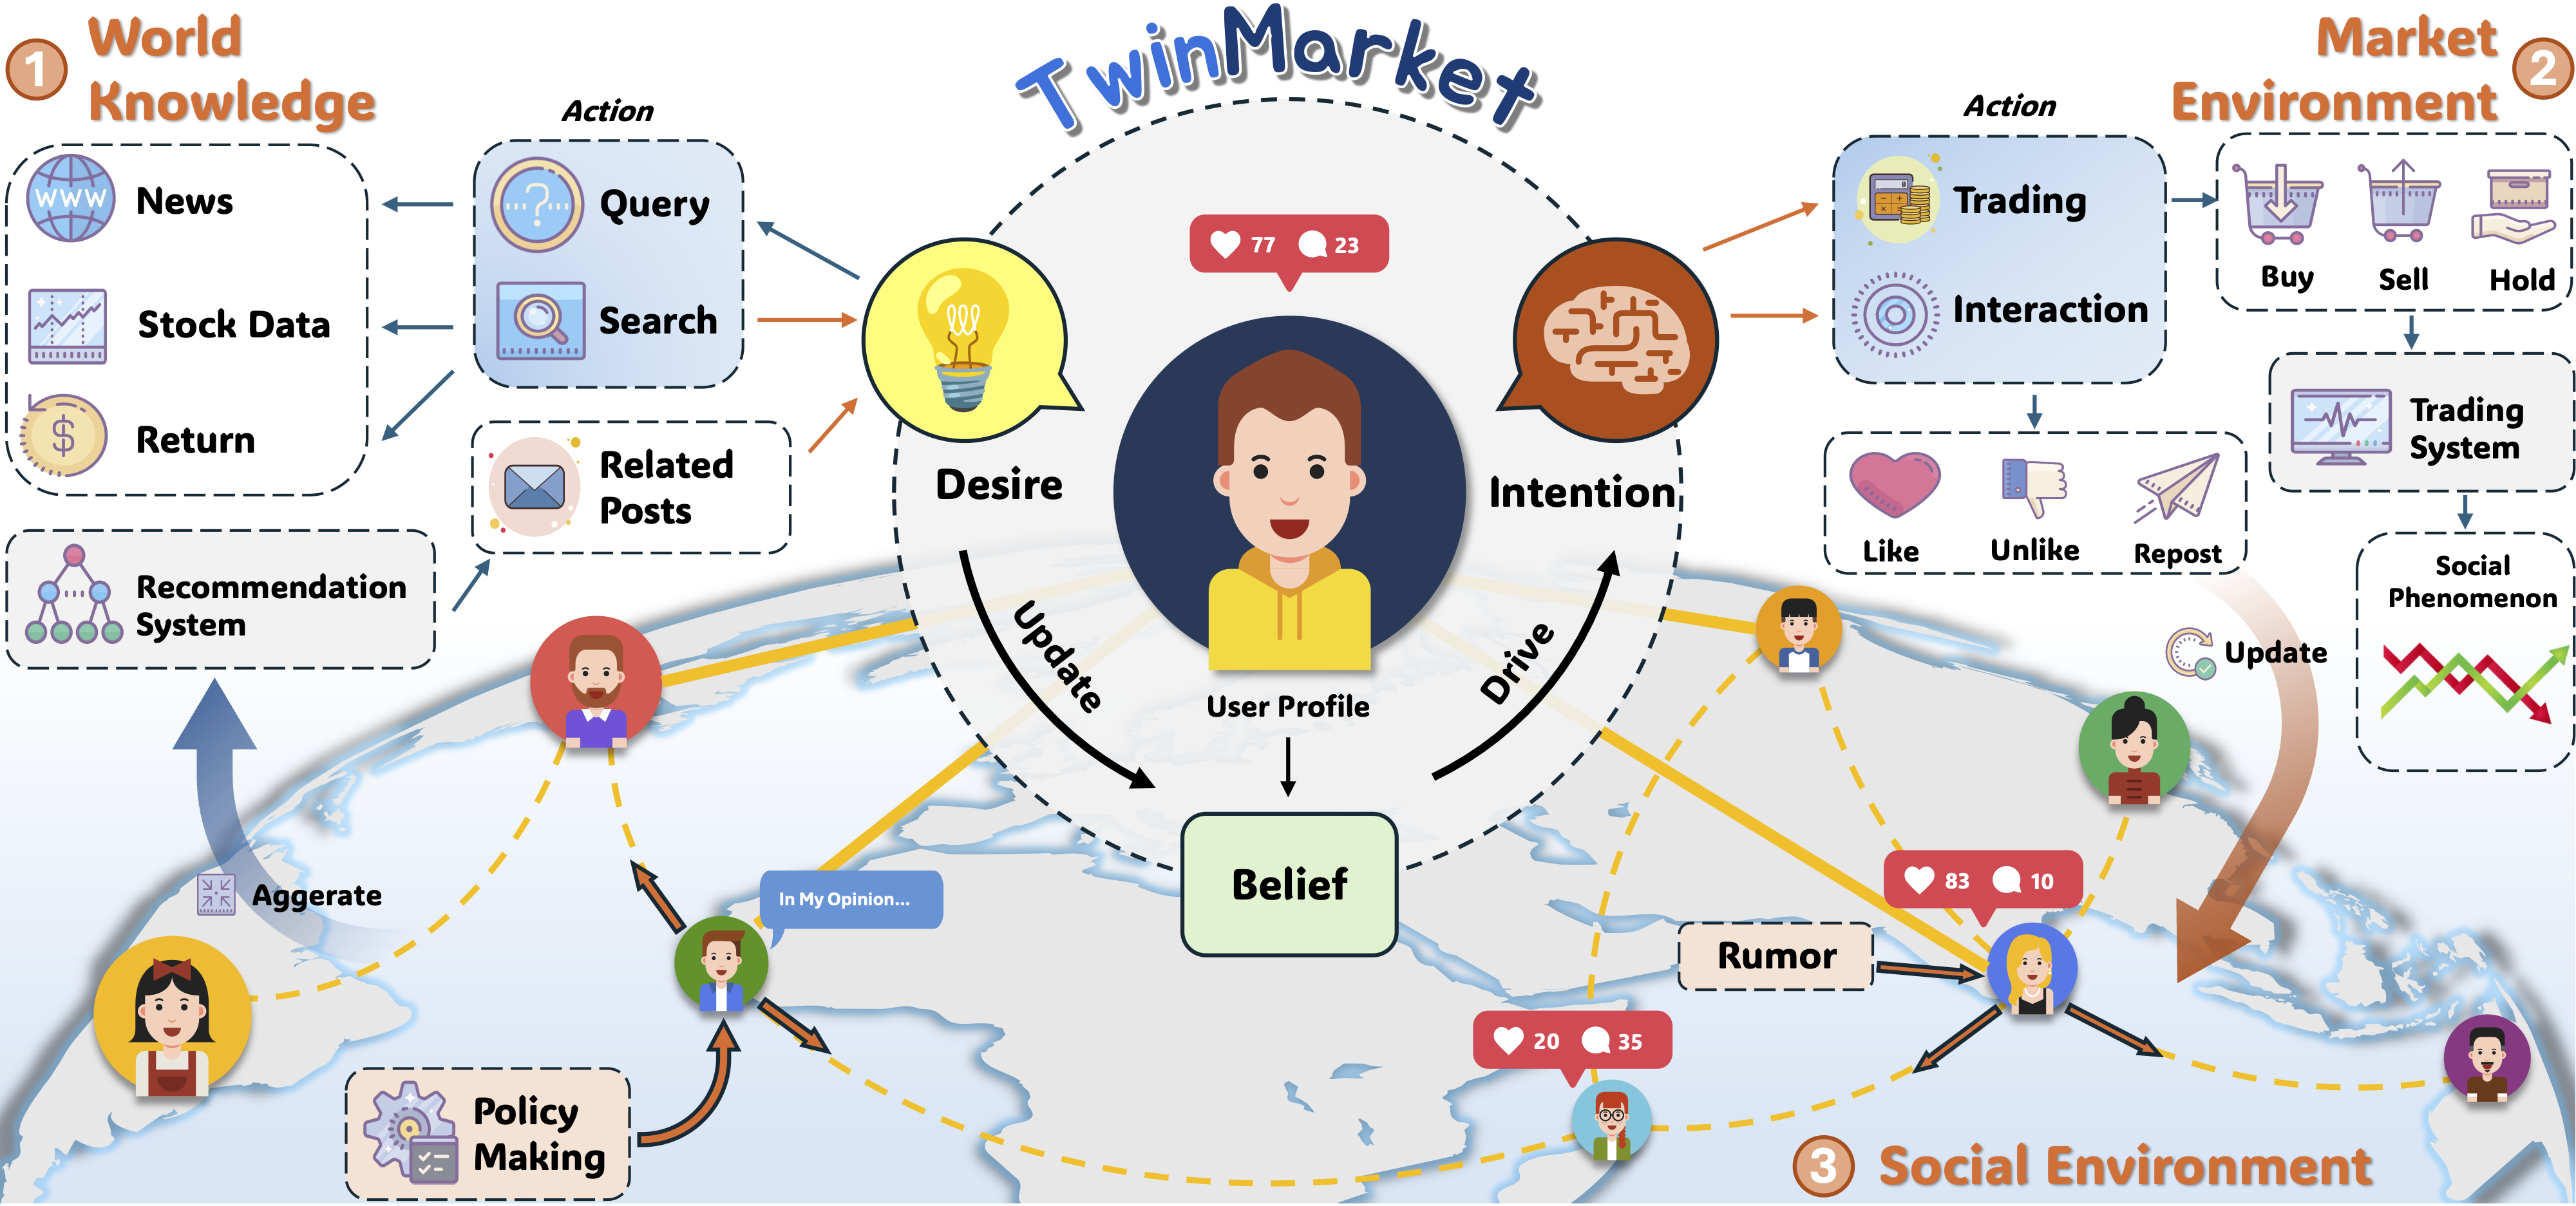
TwinMarket is an innovative stock market simulation system powered by Large Language Models (LLMs). It simulates realistic trading environments through multi-agent collaboration, covering personalized trading strategies, social network interactions, and news/information analysis for an end-to-end market simulation.
# Configure your API and embedding models
cp config/api_example.yaml config/api.yaml
cp config/embedding_example.yaml config/embedding.yaml

# Run the demo
bash script/run.sh
Implement new strategies in trader/trading_agent.py:
def custom_strategy(self, market_data):
    """Custom trading strategy"""
    # Implement your strategy logic here
    pass
Add metrics in trader/utility.py:
def calculate_custom_metric(trades):
    """Compute custom metric"""
    # Implement metric calculation here
    pass
We welcome community contributions. If your paper uses TwinMarket, feel free to open a PR and add it here.
| Title | Code | Paper |
|---|---|---|
| Interpreting Emergent Extreme Events in Multi-Agent Systems | https://github.com/mjl0613ddm/IEEE | https://arxiv.org/abs/2601.20538 |
@inproceedings{yang2025twinmarket,
  title     = {TwinMarket: A Scalable Behavioral and Social Simulation for Financial Markets},
  author    = {Yuzhe Yang and Yifei Zhang and Minghao Wu and Kaidi Zhang and
               Yunmiao Zhang and Honghai Yu and Yan Hu and Benyou Wang},
  booktitle = {The Thirty-ninth Annual Conference on Neural Information Processing Systems (NeurIPS)},
  series    = {NeurIPS},
  volume    = {39},
  year      = {2025},
  url       = {https://arxiv.org/abs/2502.01506}
}
This project is licensed under the MIT License. See LICENSE for details.
98 followers · starred Nov 2025
367 followers · starred Nov 2025
[NeurIPS 2025 & ICLR 2025 Financial AI Best Paper Award] A multi-agent framework that leverages LLMs to simulate socio-economic systems
See the code
TwinMarket is an innovative stock market simulation system powered by Large Language Models (LLMs). It simulates realistic trading environments through multi-agent collaboration, covering personalized trading strategies, social network interactions, and news/information analysis for an end-to-end market simulation.
# Configure your API and embedding models
cp config/api_example.yaml config/api.yaml
cp config/embedding_example.yaml config/embedding.yaml

# Run the demo
bash script/run.sh
Implement new strategies in trader/trading_agent.py:
def custom_strategy(self, market_data):
    """Custom trading strategy"""
    # Implement your strategy logic here
    pass
Add metrics in trader/utility.py:
def calculate_custom_metric(trades):
    """Compute custom metric"""
    # Implement metric calculation here
    pass
We welcome community contributions. If your paper uses TwinMarket, feel free to open a PR and add it here.
| Title | Code | Paper |
|---|---|---|
| Interpreting Emergent Extreme Events in Multi-Agent Systems | https://github.com/mjl0613ddm/IEEE | https://arxiv.org/abs/2601.20538 |
@inproceedings{yang2025twinmarket,
  title     = {TwinMarket: A Scalable Behavioral and Social Simulation for Financial Markets},
  author    = {Yuzhe Yang and Yifei Zhang and Minghao Wu and Kaidi Zhang and
               Yunmiao Zhang and Honghai Yu and Yan Hu and Benyou Wang},
  booktitle = {The Thirty-ninth Annual Conference on Neural Information Processing Systems (NeurIPS)},
  series    = {NeurIPS},
  volume    = {39},
  year      = {2025},
  url       = {https://arxiv.org/abs/2502.01506}
}
This project is licensed under the MIT License. See LICENSE for details.
98 followers · starred Nov 2025
367 followers · starred Nov 2025



